Buying a home in the United States involves more than agreeing on a price, getting a mortgage, and signing a deed. Before ownership changes hands, the buyer and lender need reasonable assurance that the seller has the legal right to transfer the property and that old debts, ownership disputes, or recording problems will not unexpectedly interfere with the new owner’s rights.
This is where title insurance becomes important. Unlike homeowners insurance, which generally deals with certain future losses involving the home, title insurance primarily addresses covered ownership problems connected to events that existed before the policy date. These problems may remain hidden even after public records have been reviewed.
For a homebuyer, the most useful way to understand title insurance is to view it as two layers of protection. First, the title company investigates the property’s ownership history and tries to resolve known problems before closing. Second, the insurance policy provides financial and legal protection for certain covered title problems that are discovered later.
What Does “Title” Mean When Buying a Home?
In real estate, title refers to the legal rights of ownership in a property. A deed is the document commonly used to transfer those ownership rights from the seller to the buyer, but receiving a deed does not automatically guarantee that no other person or organization has a valid claim involving the property.
For example, an earlier owner might have left unpaid property taxes, an old mortgage may have been incorrectly released, a contractor may claim an unpaid lien, or an heir may later argue that a previous transfer was invalid. Errors in recorded documents, signatures, legal descriptions, or ownership history can also create problems.
What Is Title Insurance?
Title insurance is a type of insurance designed to protect against covered financial losses resulting from defects in the title to real property. A major difference between title insurance and many other insurance products is timing. Title insurance generally focuses on covered problems connected to conditions that existed before the policy became effective.
The premium is normally paid as a one-time cost in connection with the real estate closing rather than as a recurring monthly or annual premium. The exact policy terms, coverage, price, and permitted charges vary by insurer and state, so buyers should review the actual policy and title commitment instead of assuming that every policy provides identical protection.
How the Title Search Works Before Closing?
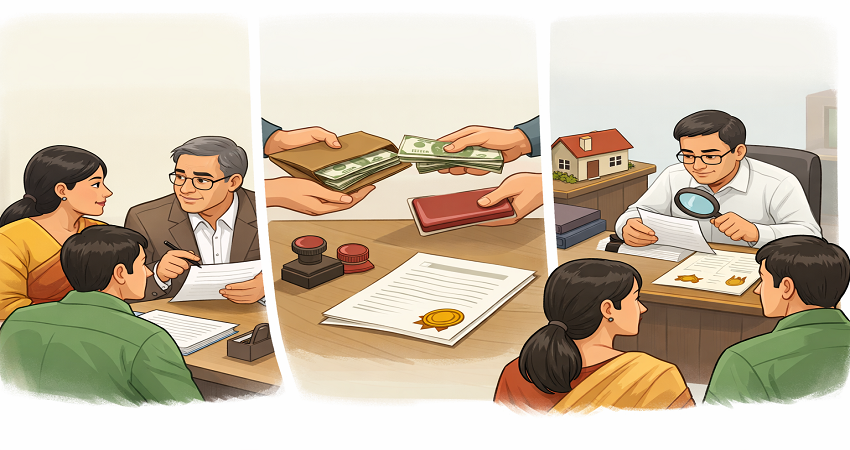
Before issuing title insurance, a title professional normally examines available public records connected to the property. The review may involve deeds, mortgages, liens, judgments, tax records, easements, recorded restrictions, court documents, and other records affecting ownership.
🔥 এই লেখাগুলো অবশ্যই পড়ুন
The purpose is not simply to produce an ownership history. The title company is trying to identify issues that must be resolved before it is willing to insure the transaction. For example, an outstanding mortgage belonging to the seller may need to be paid and released, or an error in an earlier deed may need correction.
After examining the records, the title company commonly issues a title commitment or similar preliminary document. Buyers should pay close attention to its requirements and exceptions. The important question is not only whether a title company will issue insurance, but also what that policy will and will not insure.
Lender’s Title Insurance Vs. Owner’s Title Insurance
There are two primary types of title insurance in a typical residential purchase: a lender’s policy and an owner’s policy. They protect different financial interests.
A lender’s title insurance policy protects the mortgage lender’s interest in the property. Mortgage lenders commonly require this coverage as a condition of financing. The policy protects the lender against certain covered title problems that could affect the validity or priority of its mortgage interest.
However, paying for a lender’s policy does not mean the buyer personally receives equivalent protection. If the buyer wants coverage for their own ownership interest, an owner’s title insurance policy is the relevant policy to examine.
An owner’s policy generally protects the homeowner against covered title defects that existed before the purchase but were discovered afterward. Depending on the policy and circumstances, coverage can include covered losses and legal defense costs, subject to the policy limit, exclusions, exceptions, conditions, and other terms.
What Problems Can Title Insurance Help Protect Against?
Potential title problems can take many forms. Examples may include previously unknown liens, incorrectly recorded documents, certain forged documents, mistakes in the ownership record, undisclosed ownership interests, or claims involving previous owners.
Consider a situation in which a person sells a home and an old ownership document later reveals that another individual may have retained a legal interest in the property. Another example could involve a prior unpaid obligation that resulted in a lien existing before the buyer acquired the home. Whether a specific situation is covered depends on the actual policy language.
This is why title insurance should not be viewed as a guarantee that no title problem will ever exist. It is a contract covering defined risks under defined conditions.
What Title Insurance Usually Does Not Cover?
Understanding exclusions is just as important as understanding coverage. A title insurance policy generally does not provide unlimited protection against every dispute involving a property.
Issues created after the policy date may fall outside ordinary title coverage. Certain zoning or building matters, governmental actions, environmental issues, boundary matters, survey-related problems, rights of people in possession, or defects already known to the insured may also be excluded or excepted, depending on the policy.
Specific exceptions may be listed in the title commitment or policy for the individual property. Buyers should therefore review these documents before closing and ask the title professional or a qualified real estate attorney about anything they do not understand.
How Much Does Title Insurance Cost?
There is no single nationwide title insurance price. Costs depend on factors such as the state, property value, mortgage amount, applicable rates, insurer, title services, endorsements, and the structure of the transaction.
Title-related charges may include more than the insurance premium itself. Depending on the transaction, buyers may encounter fees associated with the title search, settlement or closing services, and other title-related work.
When a mortgage is involved, title charges appear on mortgage disclosures such as the Loan Estimate and Closing Disclosure. Buyers should compare the total title-related cost rather than focusing on one line without considering how the charges have been allocated.
Can You Choose Your Own Title Company?
In many transactions, buyers can shop for certain title and settlement services. A lender, real estate professional, builder, or other participant may recommend a provider, but a recommendation should not automatically end the buyer’s comparison process.
Under federal rules applicable to covered transactions, a seller cannot require a buyer to purchase title insurance from a particular title company as a condition of the sale. State practices still vary significantly, including who traditionally selects or pays for certain services.
A useful comparison should consider total cost, licensing, insurer financial strength where relevant, responsiveness, closing experience, coverage differences, available endorsements, and how clearly the company explains the title commitment.
Who Pays for Title Insurance?
There is no universal U.S. rule saying that the buyer or seller always pays every title insurance charge. Local custom, state law, the purchase agreement, and negotiation can affect responsibility for these expenses.
In some markets the seller may commonly pay for an owner’s policy, while in others the buyer may pay it. The buyer frequently pays charges associated with a lender-required policy when obtaining a mortgage. What matters is what the contract and closing documents actually say.
What Happens If a Title Problem Appears After Closing?
If a homeowner discovers a possible title problem after purchasing the property, the first step is usually to locate the owner’s title policy and contact the insurer according to the policy’s claim procedures. Documentation should be preserved, including letters, legal notices, deeds, closing papers, and communications concerning the claim.
The insurer will determine whether the issue falls within the policy’s coverage. For a covered claim, the response could involve defending the insured’s title, attempting to resolve the defect, negotiating with another claimant, or paying a covered loss according to the policy terms and limits.
A Practical Title Insurance Checklist for Homebuyers
Before closing, confirm whether you are receiving both a lender’s policy and an owner’s policy. Review the title commitment, identify exceptions, verify that liens scheduled to be removed are actually addressed, and ask about unfamiliar easements or restrictions. Compare title providers when your transaction allows you to shop, and examine total charges rather than simply comparing one premium.
If the property has unusual characteristics, such as unclear boundary lines, multiple previous owners, inherited ownership, substantial recent construction, access questions, or complicated easements, consider whether additional legal advice, a survey, or an applicable endorsement is appropriate. The value of title work often lies in resolving a problem before ownership transfers rather than dealing with it years afterward.
Frequently Asked Questions About Title Insurance
1. Is title insurance required when buying a home?
An owner’s policy is not universally required for every U.S. home purchase. However, when a buyer uses mortgage financing, the lender commonly requires a lender’s title policy to protect its financial interest. Requirements can differ according to the lender, loan program, state, and transaction.
2. Does lender’s title insurance protect the homeowner?
No. A lender’s title policy primarily protects the mortgage lender’s insured interest. It should not be treated as a substitute for an owner’s policy. A buyer interested in protecting their own ownership investment should examine owner’s title insurance separately.
3. Is title insurance the same as homeowners insurance?
No. Homeowners insurance and title insurance address different risks. Homeowners coverage generally concerns specified losses involving the property after purchase, while title insurance primarily concerns covered defects or ownership issues connected to conditions existing before the title policy date.
4. Do I pay for title insurance every year?
Title insurance is generally purchased through a one-time premium associated with the transaction rather than through annual premiums. Additional title costs may still apply when a property is refinanced or another transaction requires a new lender’s policy.
5. What is a title commitment?
A title commitment is a preliminary document describing the conditions under which a title insurer is prepared to issue a policy. It can identify ownership information, requirements that must be satisfied before closing, and exceptions that may not be covered by the final policy.
6. Can title insurance protect against an old unpaid lien?
Potentially, depending on the type of lien, when it arose, whether it was known, and the terms and exceptions of the policy. Title searches are intended to identify recorded liens so that many of them can be resolved before closing.
7. Does title insurance cover property boundary disputes?
Not automatically. Some survey, boundary, encroachment, or off-record issues may be excluded or excepted from standard coverage. Buyers concerned about boundaries should review the policy carefully and ask whether a survey or additional coverage is appropriate.
8. Can I compare different title insurance companies?
In many home purchases, buyers can shop for certain title services. Comparing providers can help identify differences in total cost, service, coverage, endorsements, and closing support. State regulations may affect prices and how policies are offered.
9. How long does an owner’s title policy last?
A typical owner’s policy may continue protecting the insured while the insured maintains an ownership interest in the property, subject to the policy’s specific terms. Buyers should confirm duration and continuation provisions in their own policy rather than relying on a general assumption.
10. What should I check before accepting a title policy?
Review the insured owner’s name, property description, coverage amount, policy type, exceptions, easements, restrictions, liens, and any special endorsements. Make sure issues that were supposed to be cleared before closing have been handled. If an exception could materially affect ownership or use of the property, obtain a clear explanation before signing the final closing documents.
Conclusion
Title insurance is one part of a broader process designed to make a U.S. home purchase legally secure. The title search attempts to identify and resolve ownership problems before closing, while title insurance addresses certain covered defects that may surface later.
Understanding the difference between lender’s and owner’s coverage, reviewing policy exceptions, comparing title services, and asking questions before closing can help buyers make more informed decisions about one of their largest financial commitments.

Be First to Comment