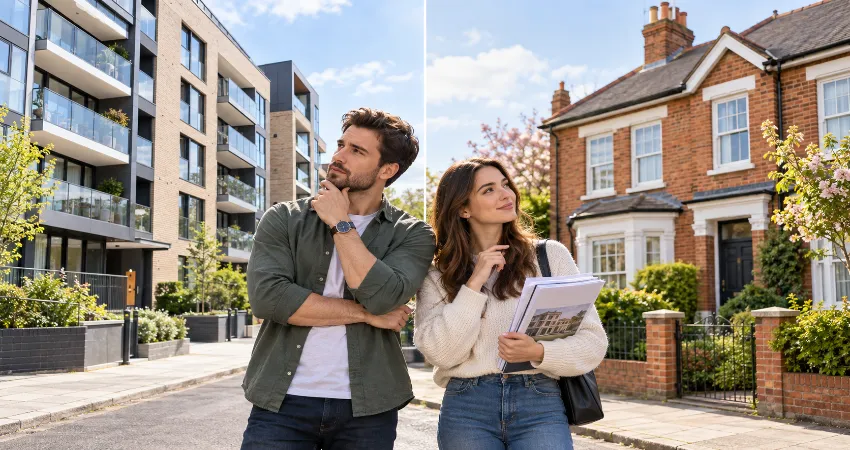
Buying your first home is already a major financial decision, but in England and Wales there is another question that can significantly affect long-term costs and control: should you buy a leasehold or freehold property? The difference is not simply a legal technicality. It can influence service charges, maintenance responsibilities, future selling options, mortgage availability and how much freedom you have to make changes to your home.
For first-time buyers, the important point is not to assume that freehold is automatically suitable or that leasehold should automatically be avoided. A well-managed leasehold flat with a long lease and sensible charges can be a practical first home. Likewise, a freehold house can still come with estate charges and substantial repair responsibilities. The better approach is to understand exactly what you are purchasing and investigate the ongoing obligations before exchanging contracts.
This guide explains leasehold vs. freehold property for first-time buyers, with a particular focus on England and Wales, where these ownership structures are most relevant. Property law differs in Scotland and Northern Ireland, so buyers there should obtain guidance specific to the jurisdiction in which they are purchasing.
What Is a Freehold Property?
When you buy a freehold property, you generally own both the building and the land on which it stands for an unlimited period. Freehold ownership is common for houses. You are usually responsible for maintaining the building, roof, garden, boundaries and other parts of the property included within your title.
The main attraction for many buyers is control. There is normally no lease that gradually becomes shorter and no separate freeholder from whom you need a lease extension. However, ownership does not mean complete freedom. Planning rules, restrictive covenants, building regulations and title conditions may still restrict alterations or the use of the property.
What Is a Leasehold Property?
A leasehold buyer purchases the right to occupy and use a property for the number of years specified in the lease. The land and usually the structure of the building remain owned by a freeholder. Leasehold ownership is particularly common with flats because multiple homes share structural areas such as roofs, entrances, lifts and corridors.
The lease is one of the most important documents in the transaction. It explains matters such as the lease length, service charges, maintenance responsibilities, insurance arrangements, restrictions and any ground rent that applies. A first-time buyer should therefore treat the lease as part of the financial assessment of the home rather than as paperwork to review only near completion.
Lease Length Can Affect the Future Value of a Flat
One of the first figures to check is the unexpired lease term. A lease with many years remaining is normally easier to deal with than one approaching the later stages of its term. Shorter leases can become more difficult to sell or finance, and extending them may involve professional fees and a payment to the freeholder.
🔥 এই লেখাগুলো অবশ্যই পড়ুন
Do not judge a property from the asking price alone. If one flat appears noticeably cheaper than similar properties in the same area, check whether its remaining lease length is one of the reasons. Ask your conveyancer to confirm the exact term from the legal documents rather than relying solely on the estate agent’s listing.
Service Charges Need Careful Investigation
Leaseholders commonly contribute towards the management and maintenance of shared parts of a building through a service charge. This may cover building insurance, cleaning, gardening, communal electricity, lifts, management services and repairs.
For a first-time buyer working with a tight monthly budget, the current service charge is only the starting point. Ask for previous service-charge accounts, the current budget and information about any reserve or sinking fund. A reserve fund can be useful because money collected over time may help pay for larger future repairs.
Most importantly, investigate planned major works. A flat with an affordable service charge today may still create a significant future expense if major roof, lift, window or external repair work is expected. Your solicitor should investigate notices, planned expenditure and relevant management information before you become legally committed.
Understand Ground Rent Before Buying
Ground rent is different from a service charge. It is a payment that may be required under the lease simply because the property is leasehold. Many qualifying new residential leases granted from 30 June 2022 in England and Wales generally have a ground rent set at a peppercorn, which effectively has no financial value.
However, purchasing an existing lease that was created earlier does not automatically remove its ground-rent terms. First-time buyers should therefore check the exact amount, review provisions and any mechanism allowing the charge to increase. Your conveyancer and mortgage lender can identify whether particular lease terms create legal or lending concerns.
Freehold Properties Can Also Have Ongoing Charges
It is a mistake to assume that buying freehold always eliminates shared charges. Some modern freehold developments require homeowners to contribute towards private roads, landscaping, communal spaces, drainage or other estate facilities. These payments are often described as estate or management charges.
That is why the tenure label should never replace proper due diligence. A freehold buyer should ask whether any management company is involved, what annual charges apply, how those charges are calculated and what services they actually fund.
Leasehold Restrictions May Affect Your Lifestyle
A lease can contain rules about how the property is used. Depending on the individual lease, permission may be required for structural alterations, replacing certain installations, keeping pets or making other changes. Some activities may be prohibited completely.
Read these restrictions in the context of your real plans. If you expect to renovate immediately after purchase, for example, ask your solicitor whether landlord or management-company consent would be required. Finding this out before exchange is much easier than discovering it after receiving the keys.
Mortgage Considerations for First-Time Buyers
Mortgage lenders assess more than the market value of a leasehold property. Lease length and particular lease provisions may affect whether a property meets a lender’s requirements. This means a home can look affordable while still presenting financing difficulties.
Do not commit money based solely on an agreement in principle. Once you have chosen a specific leasehold home, make sure your mortgage adviser and conveyancer understand the property details. Issues discovered late in the process can otherwise delay the transaction or require further negotiations.
Recent Leasehold Reforms Matter, but Check What Is Actually in Force
The Leasehold and Freehold Reform Act 2024 introduced major changes intended to improve the position of leaseholders in England and Wales. One change already implemented removed the previous requirement for many leaseholders to own their property for two years before starting certain statutory lease-extension or freehold-purchase claims.
Other reforms have been moving through implementation separately. First-time buyers should therefore avoid assuming that every measure announced under recent leasehold reform is already available in exactly the same form. Current government guidance or professional legal advice should be checked at the time of purchase.
Which Is More Suitable for a First-Time Buyer?
The answer depends on the property rather than the label alone. A freehold house can offer greater control and avoid lease-extension issues, but the owner carries responsibility for repairs and may still face estate charges. A leasehold flat can provide an affordable route into a desirable location and spread building-maintenance costs among residents, but it requires closer examination of the lease and management arrangements.
A useful buyer-focused approach is to compare the total ownership picture. Look at the purchase price, mortgage payment, council tax, insurance responsibilities, service charge, estate charge, lease length, planned works and likely maintenance costs together. That produces a far more realistic affordability assessment than comparing property prices alone.
Practical Checklist Before Making a Final Commitment
Before exchanging contracts on a leasehold property, confirm the remaining lease term, service-charge history, reserve fund, current ground rent, future review terms, planned major works, building insurance arrangements and important lease restrictions. For freehold homes, confirm boundaries, maintenance obligations, restrictive covenants and any estate-management charges. Ask questions early and make sure important answers are supported by the legal documents rather than informal assurances.
Frequently Asked Questions
1. Is freehold always better than leasehold for a first-time buyer?
No. Freehold generally offers more direct control, but suitability depends on the individual property, price and responsibilities. A long-lease flat with transparent charges and good management can suit a first-time buyer very well, while a freehold property with major repair needs may require a larger maintenance budget.
2. Can I get a mortgage on a leasehold property?
Yes, leasehold properties are routinely purchased with mortgages. However, the lender will normally consider factors such as the remaining lease term and relevant lease conditions. Buyers should disclose the property details to their lender and solicitor early in the transaction.
3. What lease length should I look for?
There is no single figure appropriate to every lender or buyer. Generally, more remaining years provide greater long-term security. If the lease is significantly shorter than comparable local properties, obtain specialist advice about mortgage requirements and possible extension costs before proceeding.
4. Does buying freehold mean I will have no annual property charges?
Not necessarily. Some freehold developments have estate-management charges for shared landscaping, roads or communal facilities. Your solicitor should establish whether such obligations are attached to the title and explain how they may change over time.
5. What does a service charge normally pay for?
It can cover shared building expenses such as maintenance, cleaning, communal lighting, lifts, building insurance, management costs and repairs. The exact services depend on the development, so buyers should examine actual accounts and budgets instead of relying on a general estimate.
6. Can service charges increase after I buy?
They can change because the cost of maintaining a building is not necessarily fixed. Insurance, repairs, utilities and management expenses may vary. Previous accounts, future budgets and information about planned works can help you understand the property’s cost history.
7. Do all leasehold properties still have ground rent?
No. Most qualifying new long residential leases granted from 30 June 2022 in England and Wales generally cannot charge more than a peppercorn ground rent. Older leases may still contain payable ground rent, so the individual lease must always be checked.
8. What are major works in a leasehold building?
Major works are substantial repairs or improvements to shared parts of a building, potentially including roofs, external walls, windows or lifts. Leaseholders may have to contribute through service charges, making planned work an important issue to investigate before purchasing.
9. Can I renovate a leasehold flat?
Often yes, but the lease may require consent for particular alterations, especially structural work. Even seemingly straightforward changes can be subject to lease conditions. Discuss your renovation plans with your conveyancer before purchase if they are important to your decision.
10. What documents should I review before buying leasehold?
Your conveyancer should review the lease, title information and management documentation. You should also pay attention to service-charge accounts, budgets, ground-rent provisions, building insurance information, planned works and relevant correspondence. Understanding these documents before exchange can prevent unexpected ownership costs later.
Conclusion
For first-time buyers, the leasehold vs. freehold decision should be based on long-term affordability, legal rights and practical responsibilities rather than the ownership label alone. Freehold can provide greater control, while a well-structured leasehold can still be an excellent first home.
Investigate the lease, charges, management arrangements and future maintenance carefully, use an experienced conveyancer and make your decision only after you understand the complete cost of owning the property.

Be First to Comment